What withholding tax actually does and who it targets
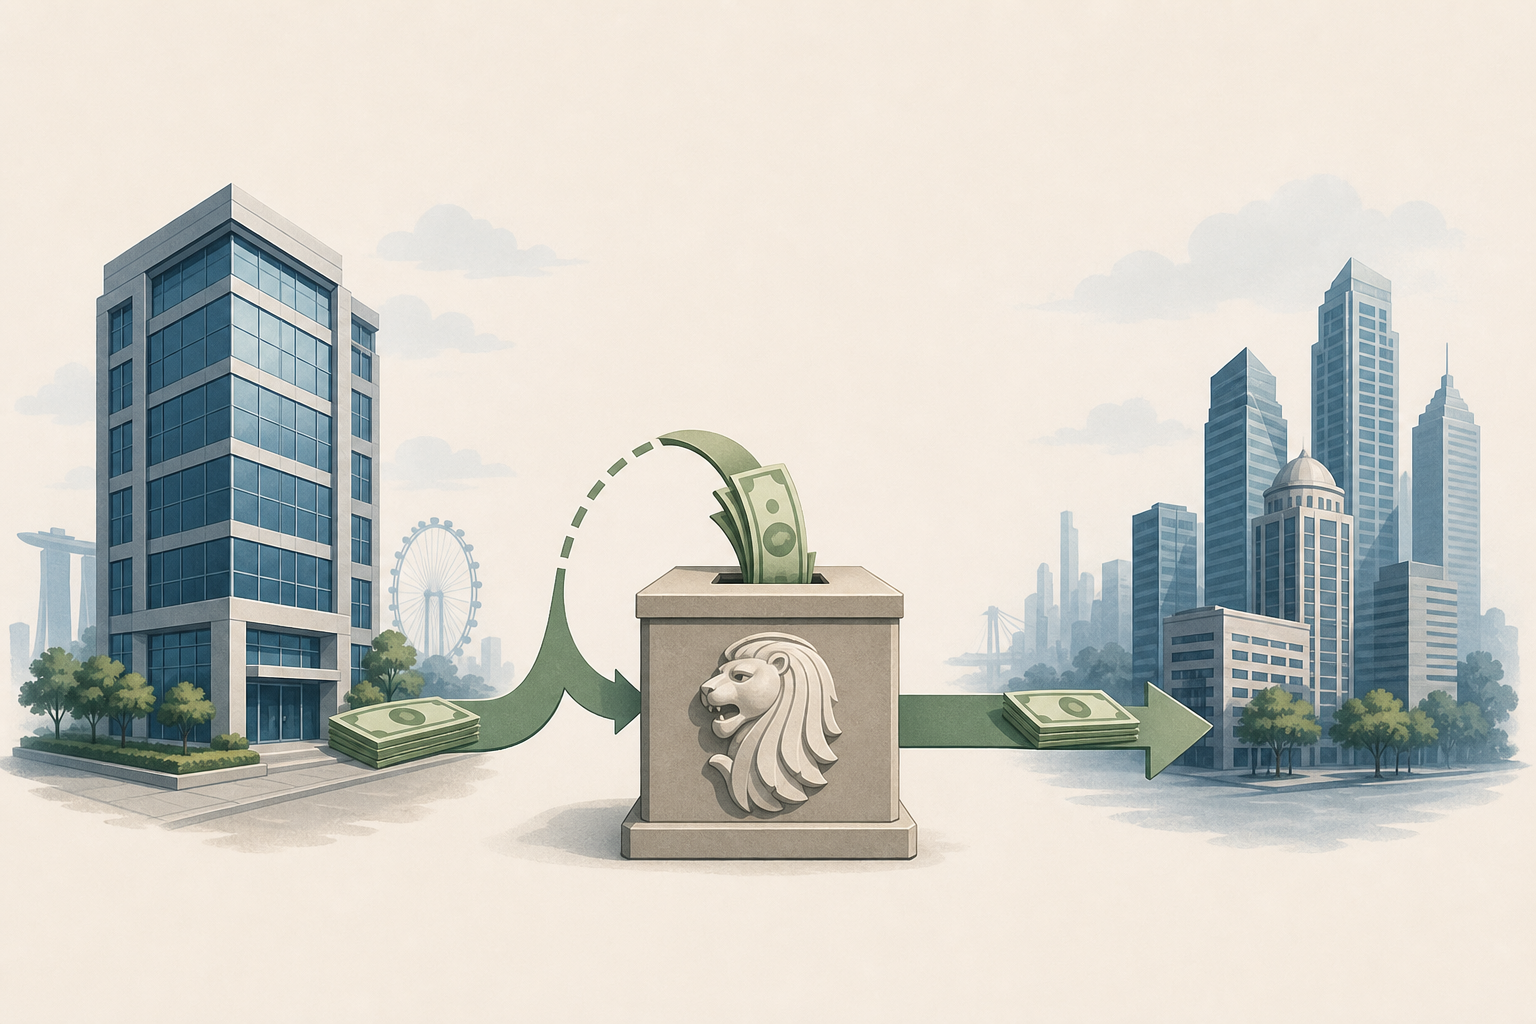
Withholding tax is not a tax on the payer. It is a tax on the non-resident recipient, collected at the source by the Singapore-based payer on behalf of IRAS. When a Singapore company pays royalties, interest, or certain service fees to a foreign company or individual, it must deduct the applicable tax from the gross payment, remit that amount to IRAS, and pay only the net balance to the recipient. The obligation sits entirely with the payer. If you fail to withhold and remit correctly, IRAS holds you, the Singapore entity, liable for the shortfall plus penalties, regardless of whether the overseas recipient has paid anything.
Which payments are caught and which are not
Not every payment to a non-resident triggers withholding tax. The Income Tax Act specifies the categories. Royalties (payments for the use of intellectual property such as patents, trademarks, and software licences) are caught. So is interest paid to a non-resident lender, technical assistance and service fees where the services are rendered in Singapore, management fees, and rent on movable property used in Singapore. Payments for goods, dividends from a Singapore company, and most payments for services performed entirely outside Singapore generally fall outside the withholding tax regime. The distinction between a service fee for work done offshore versus onshore is one of the most common points of confusion, so it is worth confirming the facts before each payment.
Rates vary by payment type and residency of the recipient
IRAS sets different withholding tax rates depending on the nature of the payment. Royalties and technical service fees are taxed at the prevailing corporate tax rate when paid to a non-resident company, and at a separate rate when paid to a non-resident individual. Interest payments to non-resident individuals carry their own rate. These are the headline rates under domestic law. Singapore's network of Double Taxation Agreements (DTAs) with many countries can reduce these rates significantly, sometimes to zero on certain payment types. The DTA rate applies only if the recipient qualifies as a tax resident of the treaty country and can produce a Certificate of Residence from their home tax authority. Always check the specific DTA before assuming a reduced rate applies. For corporate tax filing obligations more broadly, the interaction between withholding tax and your company's overall tax position is worth reviewing with a qualified adviser.
Filing and payment deadlines you cannot miss
Once a payment subject to withholding tax is made or accrued, the payer must file and remit the tax to IRAS within a set window. The standard deadline is the fifteenth day of the second month following the date the payment was made or deemed to have been made. For example, a payment made in January must be remitted by the fifteenth of March. IRAS accepts electronic filing through its myTax Portal, and payment can be made via GIRO, PayNow, or other approved methods. Late remittance attracts a penalty, and IRAS can also impose additional tax on the payer. Keeping a payment calendar and flagging every cross-border payment at the point of approval, rather than at month-end, is the most reliable way to avoid missing a deadline.
How DTAs interact with your withholding obligations
Singapore has concluded DTAs with a large number of countries, and these treaties are one of the most practically useful tools for reducing withholding tax costs. Where a DTA applies, the treaty rate replaces the domestic rate, but the payer must have the recipient's Certificate of Residence in hand before making the payment at the reduced rate. Applying a treaty rate without the certificate, and later being unable to produce it, exposes the payer to the full domestic rate plus penalties. Some DTAs also contain limitation-of-benefits clauses that prevent treaty shopping, so the recipient's structure matters as well as their country of residence. If your business regularly makes cross-border payments of the types listed above, building a DTA review into your accounts payable process, rather than treating it as a one-off exercise, will save significant administrative effort over time.
The obligation to withhold and remit sits entirely with the Singapore payer, not the overseas recipient, and IRAS will hold you liable for any shortfall.
How to handle a withholding tax payment correctly
Identify whether the payment is caught
Before any payment goes out, confirm the nature of the payment and the residency status of the recipient. Royalties, interest, technical service fees, management fees, and rent on movable property paid to a non-resident are the main categories to check. Payments for goods or for services performed entirely outside Singapore are generally not caught. Getting this classification right at the start avoids both over-withholding (which creates friction with your supplier) and under-withholding (which creates liability for you).
Check for an applicable DTA
If the recipient is resident in a country with which Singapore has a DTA, look up the treaty rate for the specific payment type. Request a Certificate of Residence from the recipient before the payment date. Without this certificate, you cannot apply the reduced treaty rate, and you must withhold at the full domestic rate. Keep the certificate on file as IRAS may request it during a review.
Calculate the withholding tax amount
Apply the correct rate, whether the domestic rate or the applicable DTA rate, to the gross payment amount. The withholding tax is deducted from the amount you would otherwise pay the recipient. Document your calculation clearly, including the rate used, the basis for that rate, and any DTA reference. This documentation is your first line of defence if IRAS queries the payment.
File and remit via IRAS myTax Portal
Log in to the IRAS myTax Portal and complete the relevant withholding tax form for the payment type. Submit the filing and remit the tax amount by the fifteenth day of the second month following the payment date. IRAS accepts payment via GIRO, PayNow, and other approved channels. Confirm receipt of the filing acknowledgement and retain it with your payment records.
Notify the recipient and update your records
Inform the non-resident recipient of the amount withheld and provide them with documentation they can use to claim a credit in their home country, if a DTA applies. Update your accounts payable records to reflect the net payment made and the tax remitted. Consistent record-keeping across every cross-border payment of this type will make your annual tax filing and any IRAS audit significantly more straightforward. For broader corporate tax compliance, see ECI filing obligations that may also apply to your company.
Benefits
Liability sits with the payer
Understanding that the Singapore payer is responsible for withholding and remitting the tax, not the overseas recipient, is the single most important point. Getting it wrong exposes your Singapore entity to penalties and back-taxes, regardless of what the recipient does.
DTAs can materially reduce the rate
Singapore's DTA network covers a large number of countries. Where a treaty applies and the recipient can produce a Certificate of Residence, the withholding tax rate can be significantly lower than the domestic rate, sometimes reduced to zero on certain payment types.
Classification of the payment is decisive
Whether a payment is a royalty, a service fee, interest, or a payment for goods determines whether withholding tax applies at all. Misclassifying a payment is one of the most common sources of error, and it can result in either under-withholding or unnecessary over-withholding.
Deadlines are fixed and penalties are real
The remittance deadline is the fifteenth of the second month following payment. IRAS imposes penalties for late remittance, and the payer cannot shift that liability to the non-resident recipient.
Withholding tax in practice: common scenarios
Singapore company licensing software from a US vendor
A Singapore-incorporated company pays a monthly licence fee to a US-based software developer for the right to use proprietary software in its business. Because this is a royalty payment to a non-resident, withholding tax applies. The Singapore-US DTA may reduce the applicable rate, but the payer must obtain a valid Certificate of Residence from the US vendor before applying the treaty rate. Failing to collect this certificate in advance means the payer must withhold at the full domestic rate, even if the treaty would otherwise have applied.
Interest paid to a foreign parent company on an intercompany loan
A Singapore subsidiary borrows from its overseas parent and pays interest on the loan. Interest paid to a non-resident is a standard withholding tax trigger. The rate depends on whether the parent's country has a DTA with Singapore and whether the parent qualifies as a tax resident of that country. Intercompany loans are a frequent area of IRAS scrutiny, so both the loan terms and the withholding tax treatment should be documented carefully from the outset.
Management fees charged by a foreign holding company
An overseas holding company charges its Singapore subsidiary a management fee for group-level services such as finance, HR, and IT support. Whether withholding tax applies depends on where the services are actually rendered. If the services are performed outside Singapore, the fee may fall outside the withholding tax regime. If any portion of the services is rendered in Singapore, that portion is likely caught. Clearly documenting where each component of the service is performed is essential to correctly applying the rules and avoiding a blanket withholding obligation on the full fee.
Technical assistance from a foreign consultant working in Singapore
A foreign consultant is engaged to provide technical training and system implementation support, and they travel to Singapore to deliver the work. Because the services are rendered in Singapore, the fees are subject to withholding tax. The payer must withhold at the applicable rate and remit to IRAS within the required window. The physical location of service delivery, not the consultant's country of residence or where the contract is signed, is the key factor that determines whether withholding tax applies.
Withholding tax in Singapore: common questions answered
Does withholding tax apply to all payments made to non-residents?
No. Withholding tax applies only to specific payment categories defined in the Income Tax Act: royalties, interest, technical service fees, management fees, and rent on movable property, among others. Payments for goods and dividends from a Singapore company are generally not subject to withholding tax. Payments for services performed entirely outside Singapore are also typically outside the regime, though the facts of each case matter.
What happens if I apply a DTA rate without the Certificate of Residence?
IRAS requires the Certificate of Residence to be in hand before the payment is made at the reduced treaty rate. If you apply a DTA rate without the certificate and cannot produce it later, IRAS can assess the full domestic rate on the payment, plus penalties for the shortfall. Collecting the certificate before each payment, not after, is the only safe approach.
When exactly must withholding tax be remitted to IRAS?
The standard deadline is the fifteenth day of the second month following the date the payment was made or deemed to have been made. For example, a payment made in March must be remitted by the fifteenth of May. Late remittance attracts a penalty, and IRAS can impose additional tax on the payer for the delay.
Does withholding tax affect my company's corporate tax filing?
Withholding tax is a separate obligation from your company's corporate income tax return, but the two interact. Amounts withheld and remitted to IRAS are generally deductible as a business expense in the payer's accounts, and the payments themselves affect your profit and loss. For your broader corporate tax obligations, including Form C filing and ECI filing, it is worth ensuring your accounting records clearly separate withheld amounts from net payments.